
Prime U.S. credit, made portable across borders.
Like LendingTree for residential purchases abroad, with lease-to-own financing arranged in the U.S.
- U.S. SSN and qualifying FICO; income verification is optional.
- U.S. agreement; payments in U.S. dollars in the U.S.
- Selected co-branded capital partners.
How proven fintech models inform Tamarindo Credit
Tamarindo Credit brings U.S. buyers and selected banks and capital partners together.
LendingTree
Connect buyers with selected financing partners
- Consumers
- Marketplace
- Financial providers
Rocket Mortgage
Customer support throughout the lease
- Borrowers
- Mortgage origination
- Ongoing servicing
Nubank
Shared technology, local workflows
- Customers
- Digital platform
- Financial products
Tamarindo Credit
Partner selection, origination and servicing
- U.S. buyers
- Tamarindo Credit
- Selected banks & capital partners
How U.S. residents fund a residence abroad
Funding routes differ in collateral, eligibility and documentation.
How Tamarindo Credit works
Tamarindo Credit manages the customer relationship from application through the lease.
U.S. buyers
Apply with a U.S. SSN and qualifying FICO.
Tamarindo Credit
Partner selection, origination and servicing.
Selected banks & capital partners
Agreed programs, terms and capacity; co-branded with Tamarindo Credit.
Local execution
Property, title and local servicing.
U.S. buyers
Apply with a U.S. SSN and qualifying FICO.
Tamarindo Credit
Partner selection, origination and servicing.
Selected banks & capital partners
Agreed programs, terms and capacity; co-branded with Tamarindo Credit.
Local execution
Property, title and local servicing.
One app. One platform. Adapted to each market.
The same U.S. customer experience. Country-specific execution.
Acquire and apply
Digital campaigns, referrals and a U.S. credit-based application.
Coordinate the transaction
Selected capital partners, local property checks and closing.
Manage the relationship
U.S. payments, servicing and the purchase option.
Planned operating platform · Product demonstration
Who we serve
U.S. residents buying where they have roots—or where they want to be.
Diaspora
A residence in their country of origin or family connection.
Destination buyers
A second residence, retirement residence or investment abroad.
Qualifying U.S. credit; income verification is optional.
Tamarindo’s Customer Acquisition and Journey
Digital distribution (app), peer-to-peer referrals and property professionals bring buyers into one Tamarindo Credit journey.
- Digital Distribution (app)
- Personal referrals
- Property professionals
- 01
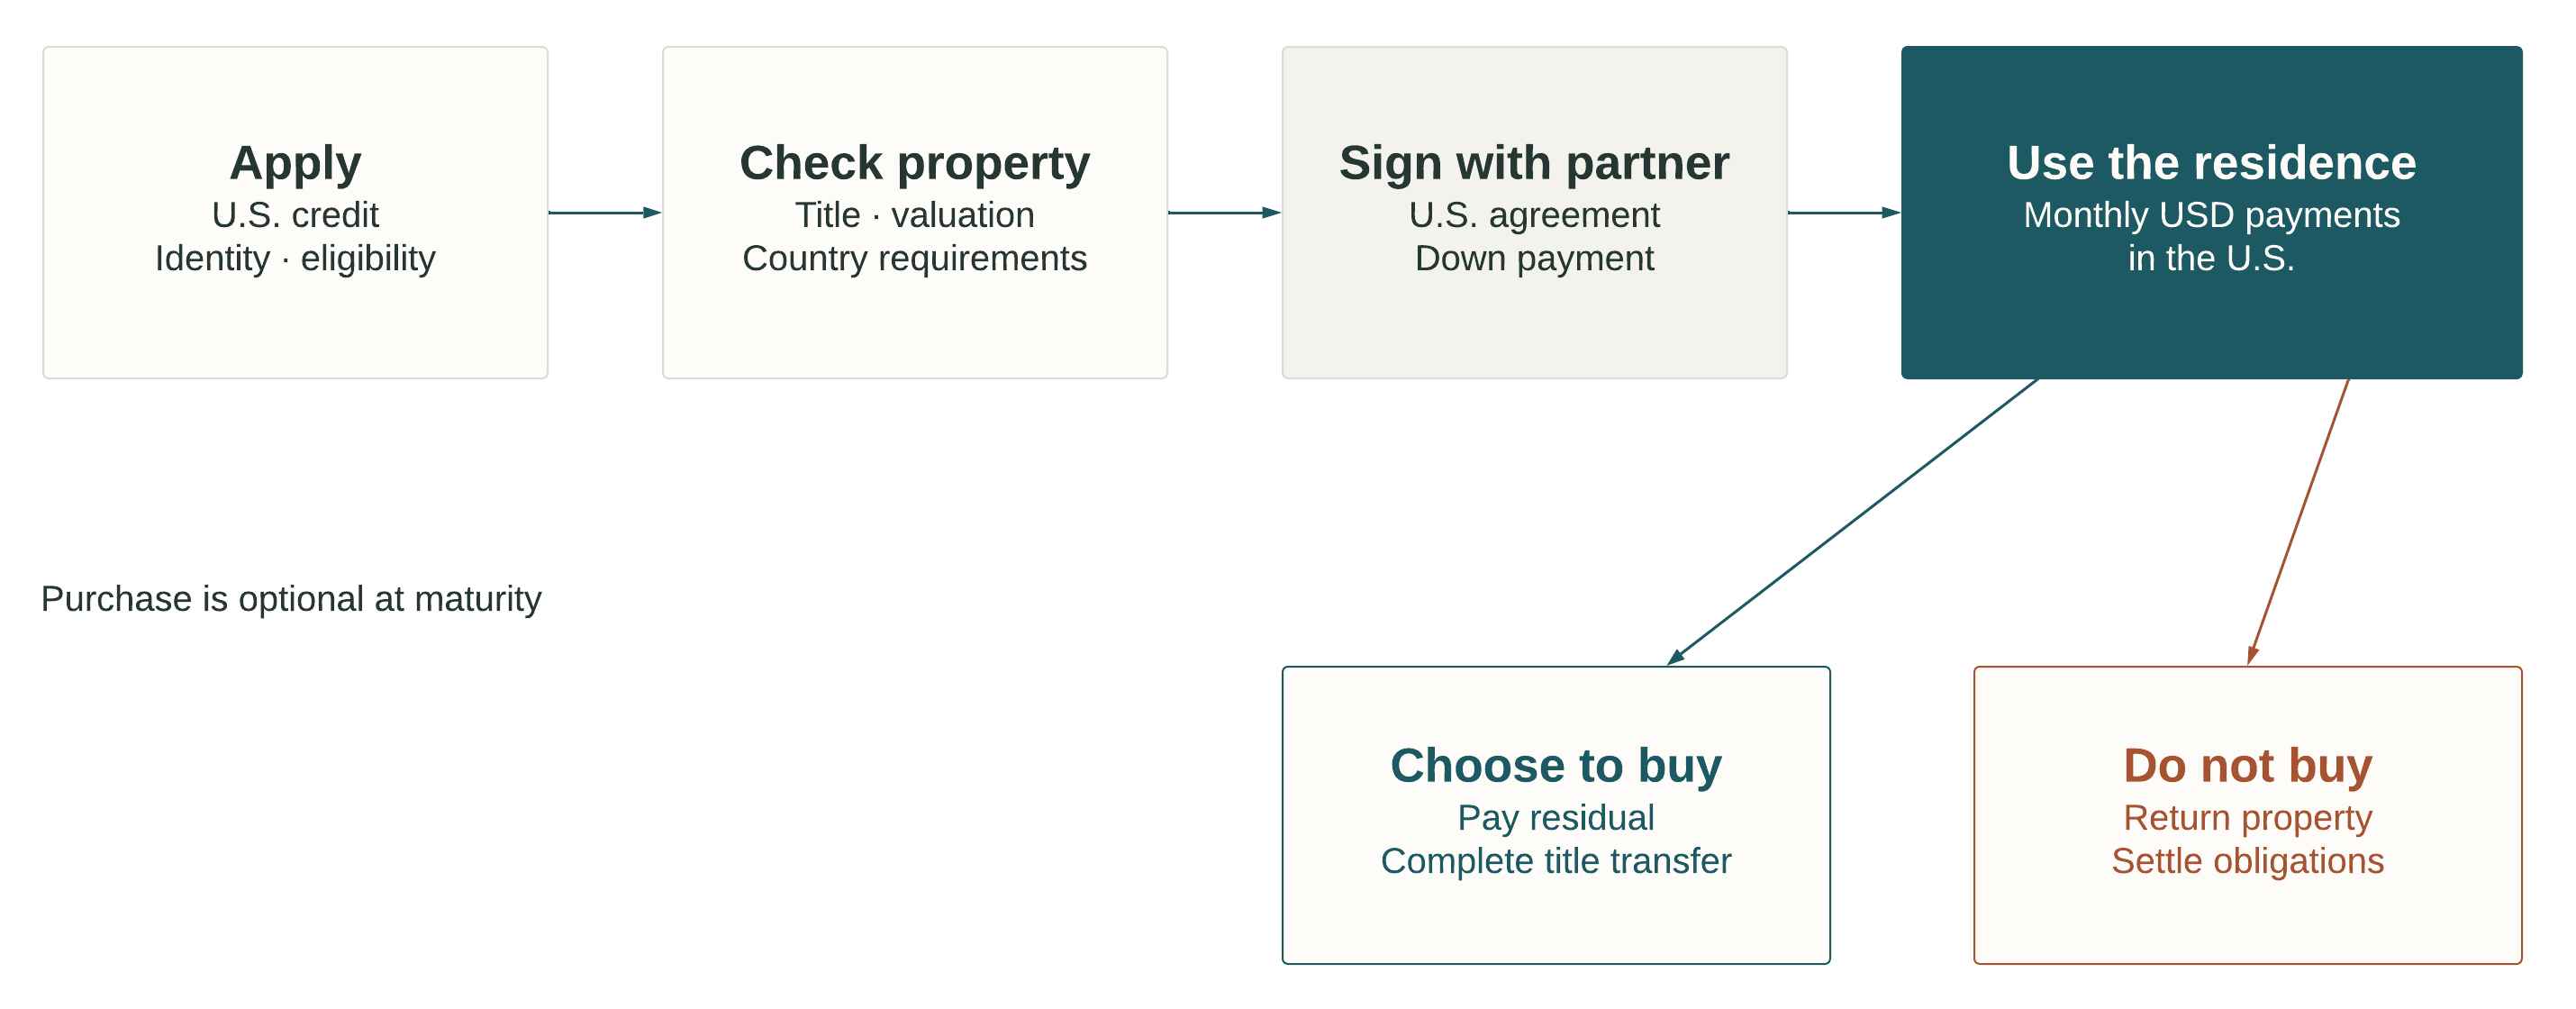
Apply
U.S. credit, identity and eligibility checks.
- 02
Check the property
Title, valuation and country requirements.
- 03
U.S. Closing
Lease-to-buy agreement signed with financing company, and down payment executed.
- 04
Occupancy and payments
Monthly USD payments in the U.S., serviced by Tamarindo Credit.
At maturity: your choice
Apply
U.S. credit, identity and eligibility checks.
Check the property
Title, valuation and country requirements.
U.S. Closing
Lease-to-buy agreement signed with financing company, and down payment executed.
Occupancy and payments
Monthly USD payments in the U.S., serviced by Tamarindo Credit.
Choose whether to buy
Purchase is optional. Pay the residual and complete title formalities, or return the property and settle contractual obligations.
What a market needs to work
We need competitive pricing and a market where a nonbank model can operate.
Competitive pricing
An attractive rate compared with local alternatives, with room for a viable return.
Nonbank regulatory framework
A clear path for our product, property ownership and operations, with licences or partners as needed.
Buyer demand
Enough qualified U.S. buyers interested in residences at our target price.
After-tax economics
Returns that work after taxes, currency exposure, funding and operating costs.
Asset protection
Enforceable property rights and a practical path to possession and sale.
Funded launch & scale
Banking, capital and partners to launch and grow at a reasonable cost.
Our rollout plan
9-month pilot
Test origination, servicing and economics.
First replication
Leverage the shared platform in a second region.
Parallel expansion
Expand in parallel with local teams and dedicated capital.
Financing programs across markets
Program pricing and local references; terms vary by borrower.
How Tamarindo Credit manages credit risk
Assess the customer, limit the amount financed and test potential losses.
Assess the customer
Review U.S. credit, obligations and repayment capacity without requiring traditional income documents.
Limit exposure
The model assumes a 35% initial payment and finances the balance.
Test the downside
Model the costs and proceeds of selling a property after a default.
The U.S. team
Leadership in capital, finance and technology.
K. Dov I. Tuzman
Executive Chairman
Founder and managing director of KIT Capital; 20+ years as an operator and investor. Former chairman and CEO of KIT Digital and COO of JumpTV. Harvard, magna cum laude.
Ricardo Cidale
CEO
Serial entrepreneur who built and sold LabOne Systems, OTT Networks and UUX Systems; led divisions at HP, Dell and RealNetworks with P&Ls over $200M. Texas A&M; Syracuse MBA.
Rosario Davi
CFO
KIT Capital CFO/COO with 24+ years in corporate finance, capital raises and debt restructuring. Previously at KIT Digital and JumpTV. Rutgers finance; MAcc and CPA candidate.
Tom Herman
CTO
Technology leader with 25 years across 10+ companies. CTO at EcoClaim; previously designed AirCarbon’s MAS-regulated emissions trading platform.
- U.S.K. Dov I. Tuzman, Executive Chairman; Ricardo Cidale, CEO; Rosario Davi, CFO; Tom Herman, CTO.
Colombia: the operating team
Leadership for the pilot, commercial relationships and growth.
Andrés Sierra
General Manager
Founder and CEO of NextWave Financial, with six years building commercial networks, strategic alliances and scalable businesses across Latin America. Co-founder of Fundación Social Conocer.
Iván Arias
EVP Corporate Dev and acting VP Sales & Marketing
President of CAA Capital Partners, with three decades building ventures across Latin America. Former KIT Digital and JumpTV executive and Colombian consul in New York.
Natalia Carvajal
Director, GTM & Growth
Marketing and business development leader with 10+ years in technology, media and education, spanning brand strategy, go-to-market, partnerships and customer acquisition.
- Andrés Sierra, General Manager; Iván Arias, EVP Corporate Dev and acting VP Sales & Marketing.
- Natalia Carvajal, Director, GTM & Growth.
The Seed offering
Tamarindo Credit is seeking $8.5M through a post-money SAFE.
- Post-money floor
- $16M
- Post-money cap
- $30.5M
- Ownership at the cap
- 27.87% before Series A
Simple agreement for future equity (SAFE)
Converts in a priced equity round. Based on Y Combinator’s U.S. post-money SAFE with a valuation cap and no discount, checked November 19, 2026.
Pilot capitalization and expansion funding
Seed equity funds the pilot. A separate FinanceCo facility would fund new leases after the pilot.
Phase 1 · Pilot funding
$8.5M
Seed SAFE
- Team and platform
- $3.5M
- Pilot leases
- $5.0M
Pilot review
Three months of setup and six months of operations.
The model projects 10 residential contracts and $5.06M in lease principal.
Management reviews actual pilot results before authorizing expansion. Actual results are pending.
Post-pilot · Expansion
$25M
Opening FinanceCo tranche
The opening tranche is proposed and unsigned. Follow-on capital is uncommitted.
- $9.6MYear 1
- $35.1MYear 2
- $77.7MYear 3
- $143.4MYear 4
- $237.8MYear 5
- $340.0MYear 6
Year 6 · Modeled results
- Net revenue
- $18.19M
- EBITDA
- $8.96M
Seed proceeds and gross returns
Seed ownership is 27.87% at the SAFE cap and 17.24% on a fully diluted basis after Series A.
Tamarindo equity at exit
$137.84M
$8.963M EBITDA × 13 + $21.33M cash
Seed share at exit
$23.77M
17.24% × $137.84M
Total gross Seed proceeds
$25.86M
$23.77M at exit + $2.09M interim distributions
Six-year success case
On $8.5M invested, before investor-level fees, taxes and carry.
- 91.9% Exit proceeds
- 8.1% Interim distributions
Thank you
Colombia Business Plan
A nine-month pilot tests the model before replication in the Philippines.
- Months 1–3
Setup
Establish the entities, hire the pilot team and prepare the origination and servicing platform.
- Months 4–9
Pilot
Close and service residential contracts in Colombia. Track demand, collections and contribution.
- After the pilot
Expansion
Review actual results before arranging the first FinanceCo tranche.
Seed equity finances the pilot leases. FinanceCo provides expansion lease capital under a separate facility.
Colombia: pricing and initial demand
Residential financing only in this model: 35% down and 65% financed, with a maximum term of 144 months.
Colombia: where Tamarindo Credit fits
Local financing is established. Our proposed lease-to-own uses U.S. credit and payments in the U.S.
Rates retain their quoted currencies and conventions; they are not USD-normalized.
Tamarindo Credit
Proposed lease-to-own
- U.S. SSN + qualifying FICO
- Income verification optional
- USD payments in the U.S.
Proposed customer terms
Purchase at maturity is optional.
Who does what in Colombia
Proposed post-pilot roles connect U.S. customer agreements with Colombian property operations.
Product permissions, tax treatment, banking controls and customer rights must be established before launch.
Colombia: Regulatory options for residential financing
Two structures under consideration for Colombian residential financing.
Colombia: the operating team
Leadership for the pilot, commercial relationships and growth.
Andrés Sierra
General Manager
Founder and CEO of NextWave Financial, with six years building commercial networks, strategic alliances and scalable businesses across Latin America. Co-founder of Fundación Social Conocer.
Iván Arias
EVP Corporate Dev and acting VP Sales & Marketing
President of CAA Capital Partners, with three decades building ventures across Latin America. Former KIT Digital and JumpTV executive and Colombian consul in New York.
Natalia Carvajal
Director, GTM & Growth
Marketing and business development leader with 10+ years in technology, media and education, spanning brand strategy, go-to-market, partnerships and customer acquisition.
- Andrés Sierra, General Manager; Iván Arias, EVP Corporate Dev and acting VP Sales & Marketing.
- Natalia Carvajal, Director, GTM & Growth.
Colombia: how TC earns
Proposed economics under the post-pilot FinanceCo arrangement.
- Tamarindo Credit also retains the agreed interest spread and liquidation surplus.
The six-year lease book
Outstanding residential principal across Colombia and the expansion markets at each year-end.
- The year-end book grows from $9.64M to $340.04M. Expansion depends on FinanceCo closing the opening tranche and securing follow-on capital.
Financing after the Colombia pilot
The pilot uses Seed equity. The expansion portfolio requires a separate FinanceCo facility.
| Financing | Model terms |
|---|---|
| Opening tranche | $25M of lease capital after the pilot. The facility has yet to be signed. |
| Follow-on funding | $370.98M in additional gross draws over the six-year forecast. Capital providers have yet to commit these funds. |
| FinanceCo equity award | $2.5M of noncash equity included in the fully diluted pre-money valuation at Series A. |
Appendix · Supporting evidenceHow we assess borrowers and collateral
The proposed process assesses credit and repayment capacity even when income documentation is optional.
U.S. credit
U.S. SSN, qualifying FICO score and payment history
Customer contribution
Initial payment and source of funds
Repayment capacity
Existing obligations and evidence accepted under the credit mandate
Property
Valuation, title, permitted use and recovery rights
Portfolio
Concentration limits, collections and stress tests
Principal recovery after a stressed sale
A $100 property starts with $65 financed and a $35 customer payment.
| Sale discount by collateral grade | Net sale proceeds | Principal shortfall | Loss on $65 financed |
|---|---|---|---|
| A · 5% | $57.72 | $7.28 | 11.2% |
| B · 10% | $54.53 | $10.47 | 16.1% |
| C · 15% | $51.33 | $13.67 | 21.0% |
- Each case assumes a 20% local price decline, 15% peso depreciation and 18 months to recover cash.
How assumed defaults affect principal loss
The table shows the share of initial portfolio principal lost under each stress scenario.
| Initial principal assumed to default | Grade A · 5% sale discount | Grade B · 10% sale discount | Grade C · 15% sale discount |
|---|---|---|---|
| 5% | 0.56% | 0.81% | 1.05% |
| 10% | 1.12% | 1.61% | 2.10% |
| 20% | 2.24% | 3.22% | 4.21% |
What financing alternatives cost
Published examples vary by currency, collateral, eligibility and fees. Ask for a transaction-specific quote.
| Financing option | Example rate | Collateral, terms or eligibility |
|---|---|---|
| Bank of America HELOC | 8.525% variable APR | U.S. home equity. September 2026 example after the introductory period. |
| Schwab Pledged Asset Line | 6.33%–8.33% variable APR | Pledged investments. November 2026 example before relationship discounts. |
| Mexico U.S. dollar mortgage | Quote required | Mexico Mortgage Hub lists up to 65% loan-to-value and a $250,000 minimum loan. |
| Second Street · Costa Rica | From 8.25% | 30-year fixed rate from the lender’s November 2025 flyer. |
| Volo · Costa Rica | Quote required | U.S.-based financing for Costa Rica homes, with fixed and adjustable options. |
| Caye Bank · Belize | 11% APR | USD loan at 50% loan-to-value. The provider lists processing fees separately. |
| BBVA · Colombia | From 14.00% effective annual | Peso mortgage for overseas residents. March 2026 salary-account rate. |
How we compare mortgage rates
Convert local mortgage rates to a USD screening basis, add sovereign risk, and show the no-doc assumption separately.
Gross sovereign CDS
Full country spread, without subtracting U.S. risk.
EMBI country spreads
Observed sovereign bond-index spreads.
Sovereign bond references
USD bond spreads; Bahamas is an estimated spread.
Comparable
USD rate
Currency-adjusted mortgage
Plus full sovereign risk
One platform, configured for each market
One customer record follows the application through servicing. Each market defines its own contracts, permissions and operating roles.
One customer record
Permissions · documents · decisions
Payments · servicing · reporting
Configure each market
Country configuration
- Eligibility and credit authority
- Contract versions and tax rules
- Banking, currency and reporting
- Vendor permissions and exceptions
Local execution
- Identity and property checks
- Valuation and legal review
- Closing and registration
- Property support and recovery
Ownership and financing in the Americas and Spain
Existing ownership and lending channels inform each market review. Tamarindo’s operating structure requires separate validation.
Colombia
Registered title and housing finance from abroad
Validate the pilot’s contracts, taxes and servicing
Mexico
Foreign-buyer finance and restricted-zone trusts
Confirm borrower eligibility, trustee charges and the default process
Brazil
Residential ownership and established bank lending
Verify credit access for U.S. residents and define local entity roles
Spain
Nonresident mortgages and intermediary registration
Identify the authorized lender, any lessor and the local servicer
Ownership and financing in Europe and Asia
The available route depends on who buys, what they buy and which provider can finance it.
Portugal
International mortgages and credit intermediaries
Match the borrower, permitted provider and total cost
Dubai / UAE
Designated-area ownership and nonresident finance
Confirm the property, corporate owner and funding terms
India
NRI and OCI residential ownership and lending
Confirm customer eligibility and which entity can own the property
Thailand
Foreign ownership of qualifying condominium units
Confirm building quota, funding requirements and purchase-option treatment
Six-year Tamarindo Credit income statement
Consolidated operating forecast for 2027–2032. Amounts in USD millions.
| USD millions, except contracts | Year 12027 | Year 22028 | Year 32029 | Year 42030 | Year 52031 | Year 62032 |
|---|---|---|---|---|---|---|
| Total contracts written | 20 | 55 | 94 | 149 | 219 | 252 |
| Total revenue | $0.96 | $3.37 | $7.03 | $12.76 | $20.85 | $29.38 |
| Less: cost recoveries from lessees | ($0.39) | ($1.39) | ($2.80) | ($4.99) | ($8.08) | ($11.18) |
| Net revenue | $0.57 | $1.98 | $4.23 | $7.77 | $12.76 | $18.19 |
| Total variable costs, net of recoveries | ($0.13) | ($0.27) | ($0.46) | ($0.71) | ($1.05) | ($1.23) |
| Total fixed costs | ($3.18) | ($4.72) | ($6.12) | ($6.88) | ($7.49) | ($8.01) |
| EBITDA | ($2.74) | ($3.01) | ($2.36) | $0.18 | $4.22 | $8.96 |
| EBITDA / net revenue | (483.3%) | (152.1%) | (55.8%) | 2.3% | 33.1% | 49.3% |
| Interest on treasury cash | $0.11 | $0.16 | $0.40 | $0.71 | $0.73 | $0.72 |
| Income before income taxes | ($2.63) | ($2.85) | ($1.95) | $0.89 | $4.95 | $9.69 |
| Income tax expense | ($0.02) | ($0.07) | ($0.15) | ($0.26) | ($0.43) | ($1.26) |
| Net income (loss) | ($2.65) | ($2.92) | ($2.10) | $0.62 | $4.52 | $8.42 |
| Net income / net revenue | (468.1%) | (147.6%) | (49.7%) | 8.0% | 35.4% | 46.3% |
Markets under consideration
Compare local mortgage references, indicative USD rates and available financing programs.
Selected rows from the 35-market comparison.
Mortgage and sovereign-risk sources linked. Select a heading to sort; scroll through all markets.
| Diaspora | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|
| 10,613,03239,788,652 | ✓ | 10.00% USD · annual | 12.27% | 150 bps | 13.77% | Direct title | Direct / trust | C · T | ||
| 3,395,7885,906,267 | — | 8.75% INR · annual | 7.57% | 150 bps | 9.07% | Residential title | OCI / permission | A | ||
| 2,236,8355,155,505 | — | 10.50% PHP · annual | 10.30% | 150 bps | 11.80% | Land and residences | Condominium route | C | ||
| 1,488,8852,693,557 | — | 7.50% USD · annual | 10.72% | 150 bps | 12.22% | Direct title | Urban title | C · T | ||
| 1,382,8882,749,468 | ✓ | 17.00% USD · annual | 18.94% | 150 bps | 20.44% | Registered title | Direct title | C · T | ||
| 846,3221,231,596 | — | 6.00% USD · annual · 15 yr | 7.50% | 150 bps | 9.00% | Registered title | Direct title | A · T | ||
| 837,441— | ✓ | 5.29% CAD · annual | 5.62% | 150 bps | 7.12% | Direct title | Ban / exceptions | C · L · F | ||
| 699,5682,067,225 | ✓ | 15.70% BRL · annual | 16.46% | 150 bps | 17.96% | Direct title | Urban title | C | ||
| 664,6861,068,919 | — | 9.10% USD · annual | 15.06% | 150 bps | 16.56% | Direct title | Area restrictions | C · T | ||
| 596,317951,296 | — | 7.41% PEN · annual | 8.61% | 150 bps | 10.11% | Direct title | Border limits | C · T | ||
| 515,38738,382,890 | — | 4.07% EUR · annual | 4.18% | 150 bps | 5.68% | Direct title | Direct title | L · T | ||
| 372,3367,705,188 | — | 6.49% PLN · annual | 6.64% | 150 bps | 8.14% | Direct title | Permit / flat | C | ||
| 385,8361,794,869 | — | 4.91% JPY · annual | 5.40% | 150 bps | 6.90% | Private ownership | Private ownership | C | ||
| 287,43715,486,240 | ✓ | 4.00% EUR · annual | 4.53% | 150 bps | 6.03% | Direct title | Reciprocity | C | ||
| 274,576378,806 | ✓ | 9.92% THB · annual | 11.00% | 150 bps | 12.50% | Land and residences | Condominium route | U | ||
| 207,248293,352 | — | 24.00% EGP · annual | 20.50% | 150 bps | 22.00% | Registered title | Regulated purchase | L | ||
| 262,340— | ✓ | 11.50% USD · annual · 15 yr | 14.49% | 150 bps | 15.99% | Private rights | Lease ≤50 years | L · T | ||
| 244,950365,479 | ✓ | 7.76% ARS · annual | 19.31% | 150 bps | 20.81% | Direct title | Urban title | C · T | — | |
| 187,601— | ✓ | 4.75% EUR · annual | 5.26% | 150 bps | 6.76% | Direct title | Direct title | C · F | ||
| 163,754405,597 | — | 9.07% RON · annual | 10.14% | 150 bps | 11.64% | Direct title | Building / land | C · F | ||
| 150,108— | ✓ | 10.08% ZAR · annual | 11.09% | 150 bps | 12.59% | Direct title | Direct title | L · T | ||
| 148,1061,240,004 | ✓ | 4.64% EUR · annual | 4.93% | 150 bps | 6.43% | Direct title | Direct title | C | ||
| 134,6871,020,251 | ✓ | 3.80% EUR · annual | 4.08% | 150 bps | 5.58% | Zone conditions | Zone conditions | C | ||
| 112,8861,114,089 | ✓ | 4.30% EUR · annual | 4.85% | 150 bps | 6.35% | Direct title | Border permit | C | ||
| 103,803— | ✓ | 7.21% AUD · annual | 6.89% | 150 bps | 8.39% | Citizen exemption | New / exempt stock | L | ||
| 115,735217,962 | ✓ | 8.25% USD · annual | 9.84% | 150 bps | 11.34% | Private title | Private title | C · T | ||
| 111,995250,442 | ✓ | 8.50% USD · annual | 9.85% | 150 bps | 11.35% | Direct title | Border limits | C · T | ||
| 98,678— | ✓ | 4.80% MAD · annual | 6.40% | 150 bps | 7.90% | Urban title | Urban title | C | ||
| 50,6082,985,206 | ✓ | 4.14% SEK · annual | 4.32% | 150 bps | 5.82% | Direct title | Direct title | L | ||
| 40,376— | ✓ | 9.25% USD · annual | 11.91% | 150 bps | 13.41% | Direct title | Register / permit | A · T | ||
| —— | ✓ | 5.58% GBP · annual | 5.92% | 150 bps | 7.42% | Direct title | Direct title | A · T | ||
| —— | ✓ | 3.54% EUR · annual | 3.70% | 150 bps | 5.20% | Mainland title | Permit / shares | L | — | |
| 18,7383,636,968 | ✓ | 6.09% NOK · annual | 6.14% | 150 bps | 7.64% | Direct title | Direct title | L | — | |
| —— | ✓ | 5.53% KRW · annual | 6.01% | 150 bps | 7.51% | Private ownership | Permit-zone rules | C | ||
| 1,243,1531,936,065 | ✓ | 15.00% COP · annual | 15.50% | 150 bps | 17.00% | Direct title | Direct title | C · F |
Criterion met Not met or unconfirmed
USD rates are screening estimates, not fully risk-priced borrower offers or executable hedges. No-doc uplift: assumed 150 bps. A marker is not a launch approval.
Pilot investment gates
The forecast passes all four gates. Management reviews actual results before authorizing expansion.
| Pilot test | Threshold for the decision |
|---|---|
| Operating contribution | Positive contribution after variable costs in operating month 6. |
| Capital drawn | Draw at least 95% of the pilot lease allocation. |
| Capital placed | Place at least 95% of the allocation into residential leases. |
| Operating fixed costs | Limit fixed costs to $1.8M over the 6 operating months. Forecast: $1.65M. |
- The forecast originates $5.06M in leases and generates $218,000 of contribution. Including setup, the pilot shows a $2.19M EBITDA loss.
Expansion funding and portfolio scale
The six-year forecast separates gross funding draws from outstanding lease principal at year-end.
| Modeled funding and portfolio | USD millions | Basis |
|---|---|---|
| Opening FinanceCo tranche | $25.0M | Proposed, unsigned facility. |
| Follow-on FinanceCo draws | $371.0M | Forecast follow-on advances. Commitments pending. |
| Total FinanceCo draws | $396.0M | Opening and follow-on advances. Gross draws can count redeployed capital. |
| Customer down payments | $204.8M | Cumulative buyer cash paid toward purchases. |
| Year 6 lease book | $340.0M | Outstanding principal at the end of Year 6. |
- The modeled client rate of 13.72% is 63 basis points above the 13.09% required rate.
Seed dilution and exit assumptions
The model assumes a $20M Series A at $60M fully diluted pre-money, including a $2.5M noncash FinanceCo equity award.
| Ownership bridge | Calculation or assumption |
|---|---|
| Seed before Series A | $8.5M invested ÷ $30.5M post-money cap = 27.87% |
| Seed after Series A | At the cap, founders and Seed retain 61.875% combined. Seed holds 17.24% fully diluted. |
| Exit equity value | 13× Year 6 EBITDA plus cash at exit yields $137.84M in modeled equity value. |
| Gross Seed return | $25.86M proceeds on $8.5M invested yield 3.04× gross MOIC. Dated cash flows yield 20.6% gross annualized IRR. |
- Final ownership and economic rights depend on the financing documents.
- 54.63% Founders and other equity
- 17.24% Seed
- 25.00% Series A
- 3.13% FinanceCo
Traction from pilot to expansion
Management reviews pilot results on project days 180 and 270. The proposed expansion scorecard adds channel and cohort reporting.
| KPI | During the pilot | After the pilot |
|---|---|---|
| Qualified demand | Offers to eligible applicants and the share accepted at quoted terms. | Applications, offer acceptance and conversion to funding by channel and market. |
| Originations | Funded contracts, funded principal and days to close. | Monthly originations, average contract size and time to close by cohort. |
| Acquisition and contribution | Acquisition cost per funded contract and contribution after variable costs. | Contribution per contract, acquisition cost by channel and fixed-cost coverage. |
| Collections and controls | Payments received versus due, plus title and insurance exceptions. | Delinquency and net loss by origination cohort. Concentrations against facility limits. |
| Market share | Define the eligible residential segment and test data coverage. | Tamarindo’s funded contracts as a share of comparable funded contracts in the same market and period. |
- Report market share where comparable market volumes are observable. Disclose the period, geography, eligibility and data coverage.